Skip to content

Mortgages for property buyers in Dubai

Buying or refinancing?

Indicative estimate only, not a mortgage offer. Banks usually lend on off plan once about half the price is paid, and only on some developers' projects; your advisor can confirm current rates and eligibility.

Estimated monthly repayment

AED 5,251/ month

over 25 years at 3.95% p.a.

Purchase price

AED

Down paymentAED 1,000,000 ·50%
Loan period25 yrs
Interest rate3.95%

Mortgages in the UAE, answered

The limits, deposits, rates and paperwork, in plain English. Updated for 2026.

Can non-residents get a mortgage in the UAE?

Yes, it is fully possible, but the choice of banks is narrower and the risk assessment is stringent. Major market players for non-resident mortgages include HSBC and Emirates NBD.

The maximum LTV (Loan-to-Value) for non-residents typically ranges from 50% to 60%, requiring a 40–50% down payment. Non-resident products also carry a premium, with interest rates usually 0.25% to 0.5% higher than those offered to residents.

What is the minimum deposit?

For a completed property, the required down payment depends on residency status, property value (with a critical threshold at 5 million AED), and transaction history. For an off plan property the cap is 50% for everyone:

Buyer profile1st property (< 5M AED)1st property (> 5M AED)2nd+ property
Off plan, any buyer50% deposit (50% LTV), whatever the buyer or the price
Non-residentTypically 40–50% deposit (50–60% LTV), set by each bank
Expat resident20% deposit (80% LTV)30% deposit (70% LTV)40% deposit (60% LTV)
UAE national15% deposit (85% LTV)25% deposit (75% LTV)35% deposit (65% LTV)

Crucial budgetary note: beyond the deposit, you must factor in upfront transaction costs (approx. 7% to 8% of the property value) payable in cash: 4% DLD (Dubai Land Department) fee, 2% agency commission, approx. 3,000 AED bank valuation fee, and 0.25% mortgage registration fee.

What rates should I expect?

Rates differ from bank to bank and depend heavily on the customer's profile and employment status (salaried vs. self-employed). Two main product types are available:

  • Fixed rate: typically locked for a period of 2 to 5 years. Market rates currently start around 3.9% to 4.9% (the best rates usually require transferring your salary to the lending bank).
  • Variable rate: linked to the EIBOR (Emirates Interbank Offered Rate) plus a fixed bank margin (typically between 1.75% and 2.5%).

Salaried applicants generally receive slightly more favourable interest rates and lower processing fees compared to self-employed individuals.

How much can I borrow?

As a general rule of thumb, the maximum mortgage limit can reach up to 84x the monthly salary (7 years of annual income) for expat residents and up to 96x (8 years) for UAE nationals. However, the final approval heavily depends on individual bank policies and risk assessments.

While the Central Bank of the UAE technically sets the maximum DBR (Debt Burden Ratio) at 50%, in practice banks are much more conservative. To mitigate risk, lenders typically cap the maximum mortgage payment at around 35% of your monthly net income.

Example calculation

Monthly salary
10,000 AED
Max monthly mortgage payment (35%)
3,500 AED
By the payment (3,500 AED × 12 months × 25 years)
~1,050,000 AED
By the income cap (84 × 10,000 AED, expat resident)
840,000 AED
Max loan (the lower of the two)
~840,000 AED

Keep in mind that every active credit card directly reduces your borrowing capacity. The bank automatically factors in 5% of the card's total credit limit as a fixed monthly expense, even if your current balance is zero.
What documents do I need?

Buying from outside the UAE

  • Your passport.
  • The income documents below (salary certificate and payslips, or company papers), from your employer or company abroad.
  • Personal bank statements from your home bank for the last 6 months.
  • Your advisor sends the exact list for your bank.

Salaried applicants in the UAE

  • Identification documents (passport, residence visa, Emirates ID).
  • Current salary certificate addressed to the bank.
  • Personal bank statements for the last 3 to 6 months (showing salary credits).
  • Payslips for the last 6 months and complete details of existing liabilities.

Self-employed applicants in the UAE

  • ID documents of the shareholders and full company papers (trade licence, MOA, shareholder certificate).
  • Audited financial statements of the company (typically for the last 2 years).
  • Corporate bank statements for the last 12 months.
  • Personal bank statements for the last 6 months and full details of existing liabilities.
How long does a pre-approval take?

The standard turnaround time to receive a formal pre-approval letter is 5 to 7 working days once a complete set of required documents has been submitted to the bank.

Initial observations, additional queries, or missing document requests are normally communicated by underwriting within the first 2 working days. The entire end-to-end mortgage transaction (from pre-approval to final deed transfer at the registration trustee) usually takes 3 to 6 weeks.

Projects in the UAE

10/30/60 Payment Plan

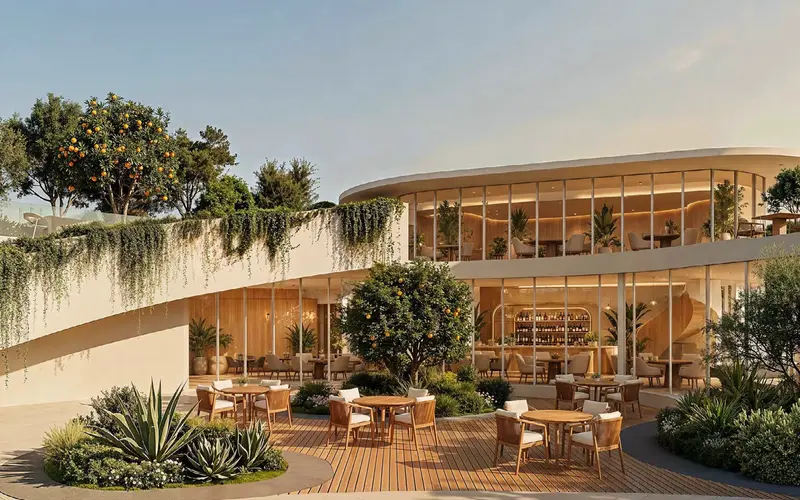
Arancia Yards

BEYOND, Dubai | City Of Arabia

Apartment · 1–3 beds

Starting from
AED 1,000,000
Est. mortgage
AED 2,625/mo
Payment plan40/60
HandoverQ1 2029
Hot Deal

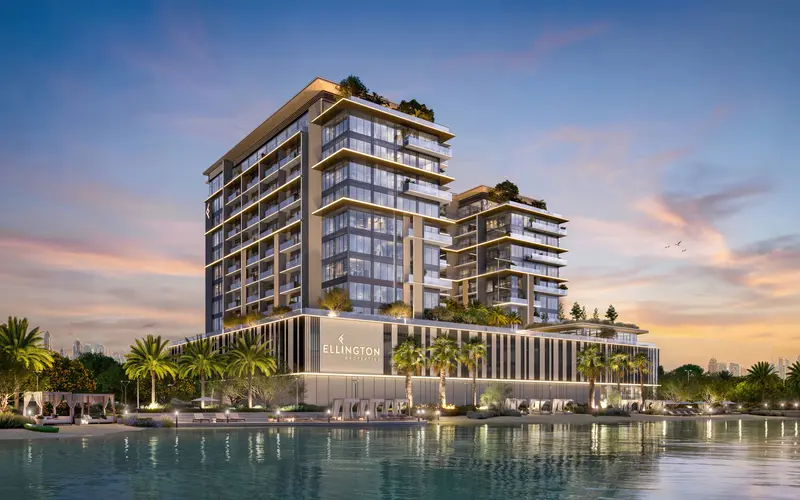
Ellington Everly Place

ELLINGTON, Dubai | Bukadra MBR

Apartment · 1–3 beds

Starting from
AED 1,900,000
Est. mortgage
AED 4,988/mo
Payment plan70/30
HandoverQ4 2029
Hot Deal

Palm Central Private Residences

NAKHEEL, Dubai | Palm Jebel Ali

Apartment · 1–4 beds

Starting from
AED 2,700,000
Est. mortgage
AED 7,089/mo
Payment plan70/30
HandoverQ3 2030
See all projects

Talk to a mortgage advisor

Share a few details and one of our advisors will come back with options that fit your budget and plans. No obligation.

  • Straight answers from a licensed team

Prefer to talk it through first?

Chat with us on WhatsApp

By submitting, you agree to our Terms and Conditions and our Privacy Policy.

Prefer to talk it through first?

Chat with us on WhatsApp